In this guide
Pension salary sacrifice can reduce the take-home cost of pension saving. You agree to give up future cash salary, and your employer pays the agreed amount into your pension instead. The benefit depends on your earnings, pension arrangement and circumstances.
A £1,200 example
Imagine an employee earning £30,000 who wants an extra £1,200 a year in their pension. Compare an ordinary employee contribution under a net-pay arrangement with a valid salary-sacrifice arrangement funding the same £1,200.
This simplified 2026/27 example assumes the whole amount falls within the employee's 20% Income Tax and 8% National Insurance bands. Existing employer pension contributions stay unchanged. There are no other deductions or benefit changes, and reduced cash pay still meets minimum-wage rules.
| Annual effect of funding this £1,200 | Employee contribution: net pay | Salary sacrifice |
|---|---|---|
| Added to pension | £1,200 | £1,200 |
| Income Tax reduction | £240 | £240 |
| Employee NI reduction | £0 | £96 |
| Reduction in take-home pay | £960 | £864 |
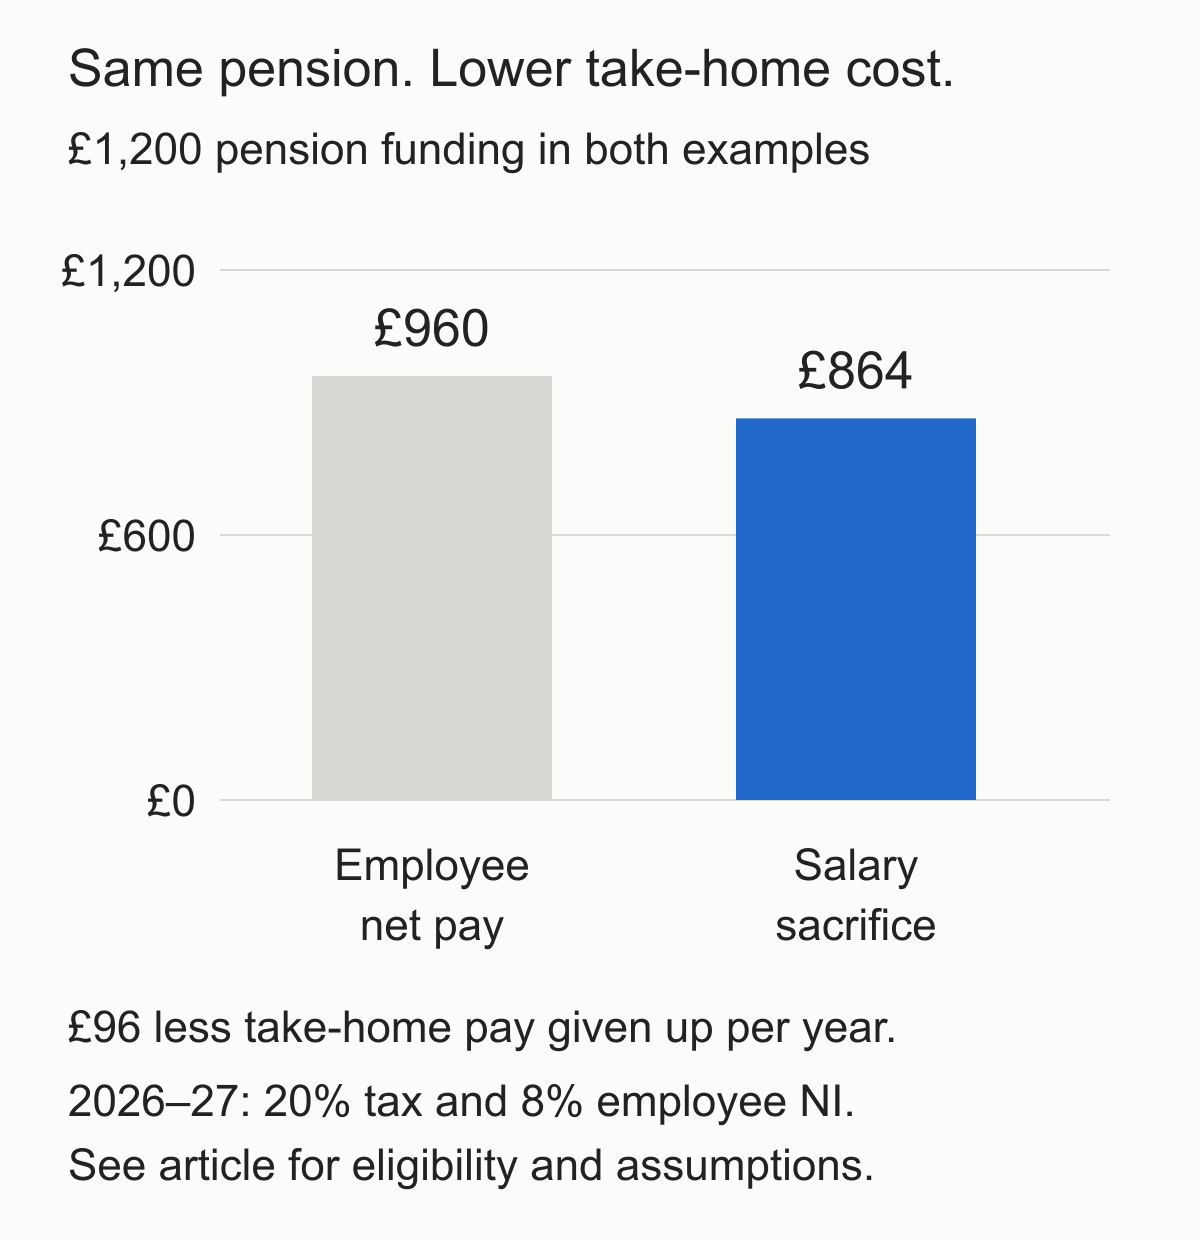
The extra take-home benefit is £96. Ordinary net-pay pension contributions already receive Income Tax relief, so the £240 is not an additional salary-sacrifice saving. GOV.UK explains net-pay pensions.
At a standard 15% employer NI rate, the employer's liability also falls by £180 on the £1,200 exchanged. That is before any Employment Allowance or Corporation Tax effect. If Employment Allowance already covers the liability, the cash saving may be smaller or nil. Ask whether any employer saving is retained or added to the pension; the example assumes none is shared. Current payroll rates.
Check these points before agreeing
- Confirm whether your pension uses net pay or relief at source; the payslip comparison differs.
- Ask payroll for your own before-and-after figures, including statutory-pay and other benefit effects.
- Check that reduced cash pay stays above the applicable minimum wage for your hours.
- Agree the future contract change and confirm that the pension provider supports the arrangement.
- Check pension allowance limits and how any existing employer contributions are calculated.
Lower cash earnings can affect statutory payments and other earnings-related benefits. Pension money is also subject to pension access rules, so it will not replace cash needed for current bills. HMRC's salary-sacrifice guidance explains the setup and risks; pension allowance rules need a separate check.
Ask your employer or payroll adviser for a comparison using your actual pay and pension scheme before opting in. Swift's Payroll and Pensions service can discuss payroll work within an agreed scope.
Read our guide to auto-enrolment pension duties. Swift’s Payroll and Pensions service can discuss payroll work within an agreed scope.
Need help running payroll?
Run payroll and agreed pension tasks to a set timetable, with employee changes and approvals tracked each pay period. We agree the scope and fee before work starts.
Discuss your payroll